
What is a Starter Interrupt
Device on a Financed Car?
When you are exploring financing options for a used car, especially through in-house financing programs, you might come across the term "starter interrupt device" or "payment assurance device." Understanding what this is can help you feel more confident in your purchase. Simply put, a starter interrupt device is a small piece of technology connected to your vehicle’s ignition system. Its primary function is to serve as a security measure for the financing agreement. If a payment is seriously past due and attempts to contact the borrower are unsuccessful, the device can be used to prevent the car from starting. This technology is often used by lenders who provide opportunities for individuals with complex credit histories, as it helps manage the risk involved in the loan. It acts as an automated payment reminder system, helping you stay on track and successfully complete your loan, ultimately paving the way to full ownership of your vehicle.
It is important to know that the use of these devices is a standard practice for many lenders who specialize in helping people rebuild their financial standing. The terms regarding the device will be clearly disclosed in your financing paperwork, ensuring complete transparency from the start. Our goal is not to use this technology, but to partner with you for a successful loan experience. Open communication is key, and we encourage you to contact us if you ever anticipate having trouble with a payment. We are here to work with you.
A Deeper Look at Payment Assurance Technology
Navigating the world of automotive financing can introduce you to terms and technologies you may not have encountered before. The starter interrupt device (SID) is one such piece of technology. While it might sound intimidating, its purpose is straightforward: to secure the asset—the vehicle—for the lender who is extending the credit. This is particularly common in Buy Here Pay Here (BHPH) and other in-house financing scenarios where the dealership itself is acting as the bank. By financing the vehicle directly, dealers can create opportunities for buyers who may not qualify for a traditional bank or credit union loan.
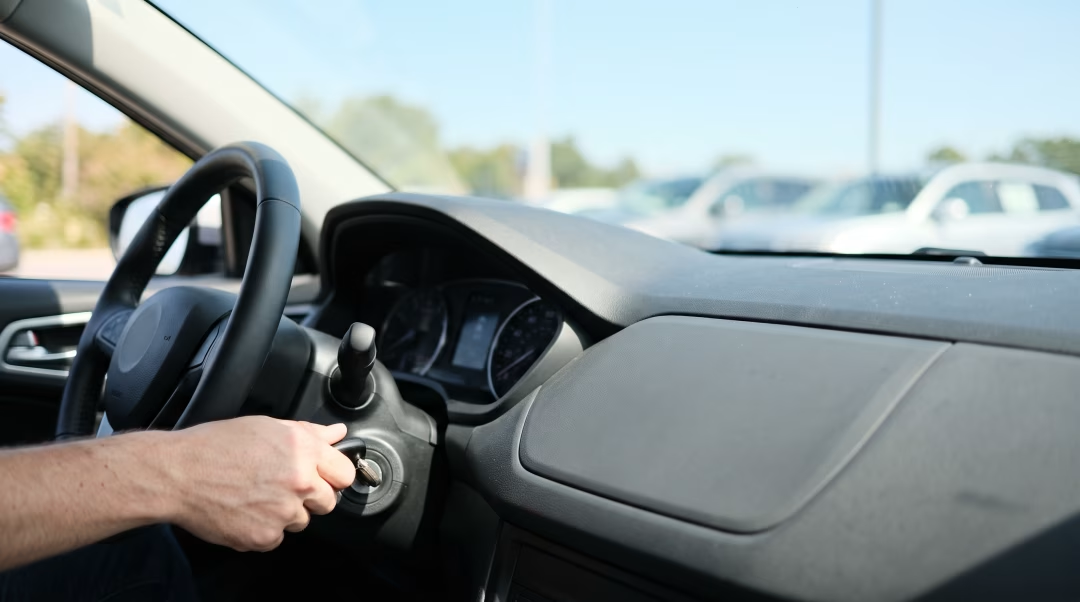
The technology itself is relatively simple. A small module is professionally installed in a discreet location within the vehicle and connected to the starter mechanism. It does not interfere with the vehicle's normal operation in any way when your account is in good standing. Many of these devices also include GPS capabilities. This is not for constant monitoring of your daily drives but serves as a tool for vehicle recovery in the unfortunate event of a loan default and subsequent repossession. The use of these devices allows lenders to have more confidence in extending financing, which in turn means more people get the chance to purchase a reliable car.
Why Lenders Use Starter Interrupt and GPS Devices
The primary reason some Dallas dealers offer in-house financing and use this technology is risk management. Traditional lenders often rely heavily on credit scores to determine a borrower's likelihood of repaying a loan. However, in-house financing lenders understand that a credit score does not tell the whole story. People face unexpected challenges like medical debt, divorce, or job loss that can negatively impact their credit. By using a payment assurance device, the lender can mitigate the financial risk associated with lending to someone with a lower credit score or a thin credit file. This security makes them more willing to approve applications that might otherwise be denied.
Think of it as a safety net for the lender. This net allows them to extend financing to a broader community of drivers. Without it, many individuals would be left with no viable options for purchasing the essential transportation they need for work, school, and family life. The device serves two main purposes in this context:
- Payment Reminders: Many devices are programmed to emit a gentle beeping sound or flash a small light a day or two before a payment is due. This serves as a helpful, low-key reminder to make your payment on time, helping you stay on schedule and build a positive payment history.
- Asset Protection: In a worst-case scenario where a borrower stops making payments and ceases all communication, the device enables the lender to protect their asset. The starter interrupt function can be activated, and the GPS can be used to locate the vehicle for recovery. This is always a last resort.
The Borrower Experience: What to Expect
Living with a starter interrupt device on your car is largely uneventful. For the vast majority of the loan term, you will not even know it is there. The only interaction you might have with it is the periodic payment reminder. The process is designed to be as non-intrusive as possible. If you make your payments on time, you will never experience the "interrupt" function. The entire agreement is detailed in your retail installment contract, ensuring there are no surprises.
The critical takeaway is the importance of communication. Life happens, and we understand that. If you foresee an issue with an upcoming payment—perhaps your hours were cut at work or you had an unexpected emergency expense—the single most important thing you can do is contact your lender before the due date. Lenders would much rather work with you to find a solution, such as a payment deferral or a temporary arrangement, than resort to disabling the vehicle. Disabling a vehicle is a final step taken only after a payment is significantly late and multiple attempts to reach the borrower have failed. Proactive communication can prevent this from ever becoming an issue.
After the Final Payment: Completing Your Journey
Successfully paying off your auto loan is a huge accomplishment, especially if you started with a challenging credit situation. It is a moment to be proud of. Once you have made your final payment and the loan is officially paid in full, what happens to the starter interrupt device? The process is simple. You will contact the dealership, and we will remotely and permanently deactivate the device. It will no longer have any function and will not affect your car in any way. In most cases, the device is simply left in place, as removing it involves dismantling parts of the dashboard and is unnecessary once deactivated. Completing your loan not only means the device is turned off for good, but it also means you will receive the vehicle's title, making you the full and clear owner of the car. This positive payment history can also be a significant step toward improving your credit profile for the future.
Can a dealer disable my car without any warning in Texas?
Generally, the device is used after a payment is already past due. Many devices provide audible or visual alerts inside the car before a payment due date as a reminder. The specific terms regarding when the device can be activated will be clearly outlined in your financing agreement. This is why it is crucial to read and understand your contract. For more information, you can read about late payment policies in Texas.
Will a starter interrupt device cause any damage to my vehicle?
No, when installed correctly by a trained technician, these devices are designed to integrate safely with your vehicle’s electrical system. They only interact with the circuit that allows the starter to engage. They do not affect the engine, transmission, or any other critical operating components of your car. The device simply prevents the starter from cranking the engine and does not cause harm.
Who is responsible for the cost of the device and its installation?
The cost of the device and its professional installation is typically absorbed by the lender as a part of their cost of doing business. This cost is factored into the overall financing structure but is not usually presented as a separate, direct fee to the customer. It is part of the package that allows the lender to offer in-house financing.
Is it possible for me to remove or tamper with the device myself?
You should never attempt to remove, disable, or tamper with a starter interrupt device. Doing so is a violation of your financing agreement and can have serious consequences, including immediate default on your loan. These devices are installed securely, and attempting to remove them could also cause significant damage to your vehicle's electrical system, leading to expensive repairs for which you would be responsible.
Is the GPS feature constantly tracking my every move?
Lenders who use GPS-enabled devices are primarily concerned with asset protection, not personal surveillance. The GPS functionality is typically only accessed in specific, contractually defined circumstances, such as a loan default, to locate the vehicle for recovery. The lender’s policy on GPS data access should be disclosed in your financing paperwork. For more insight, you can learn about why in-house dealers use GPS devices.
